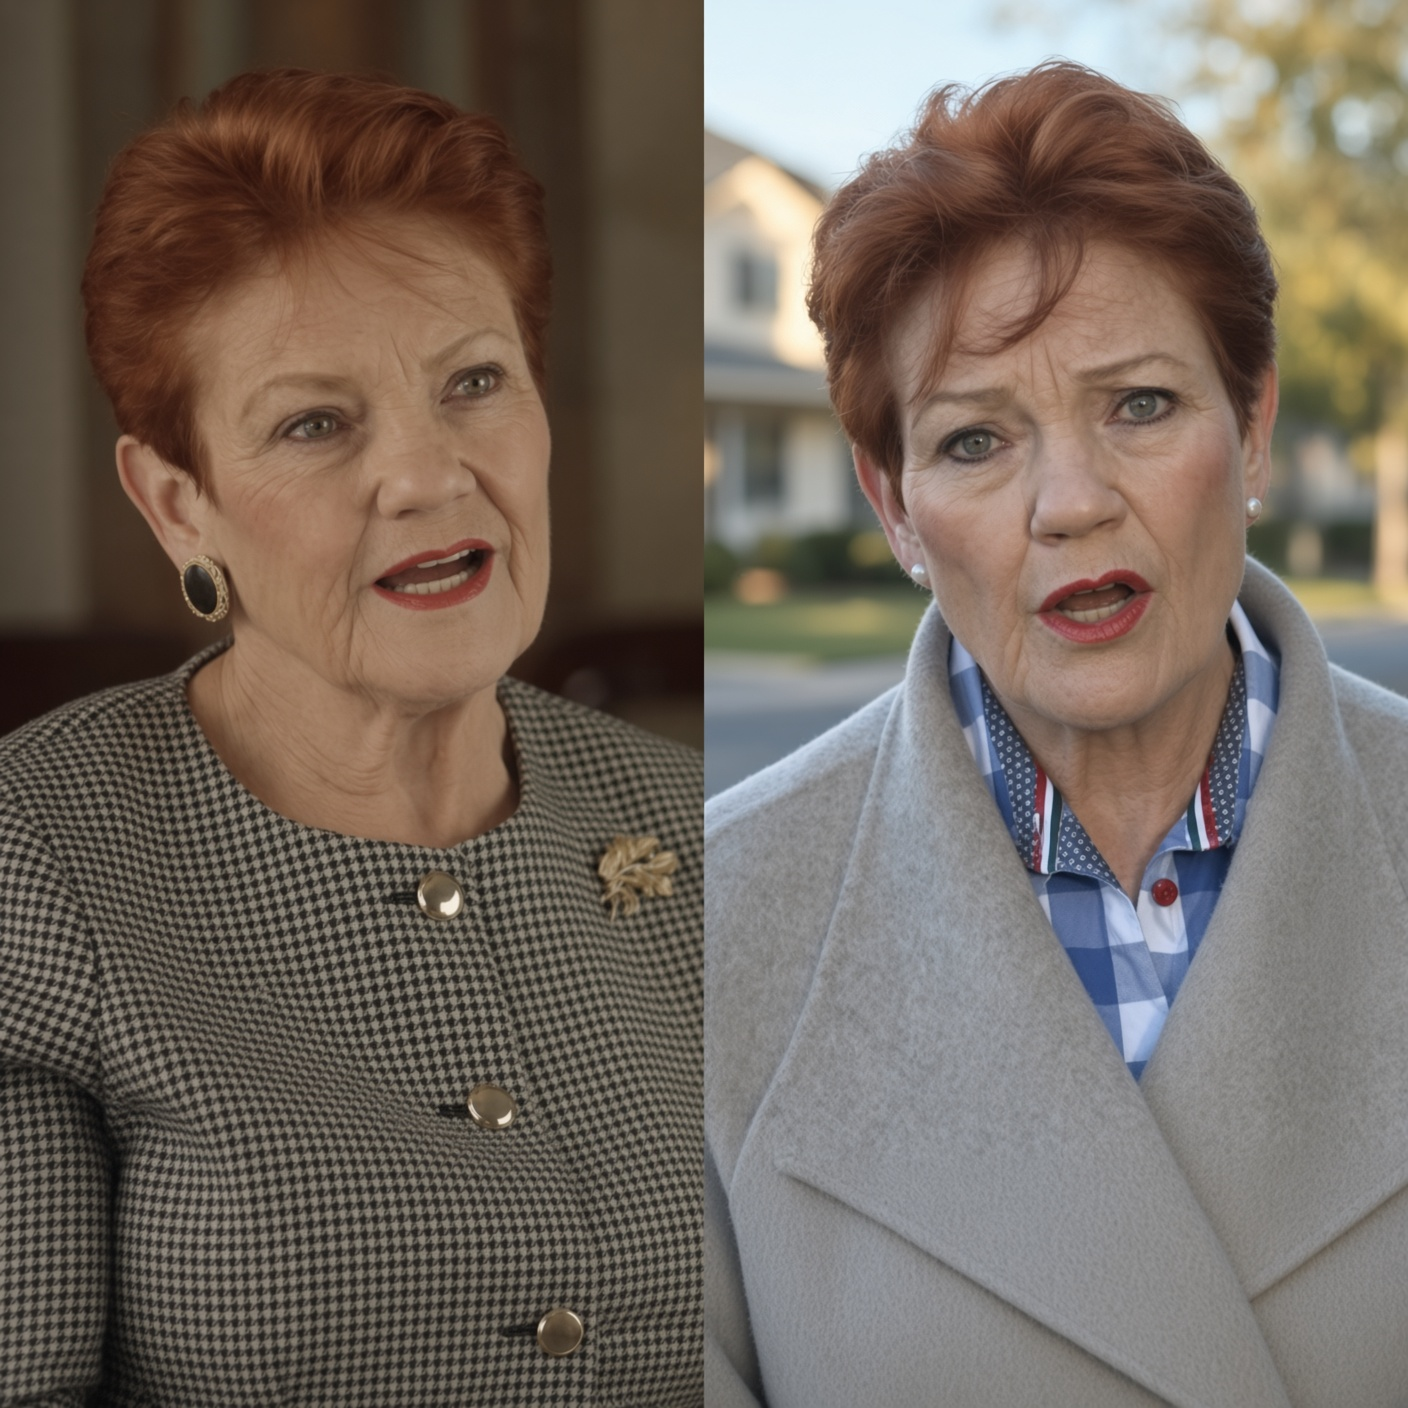
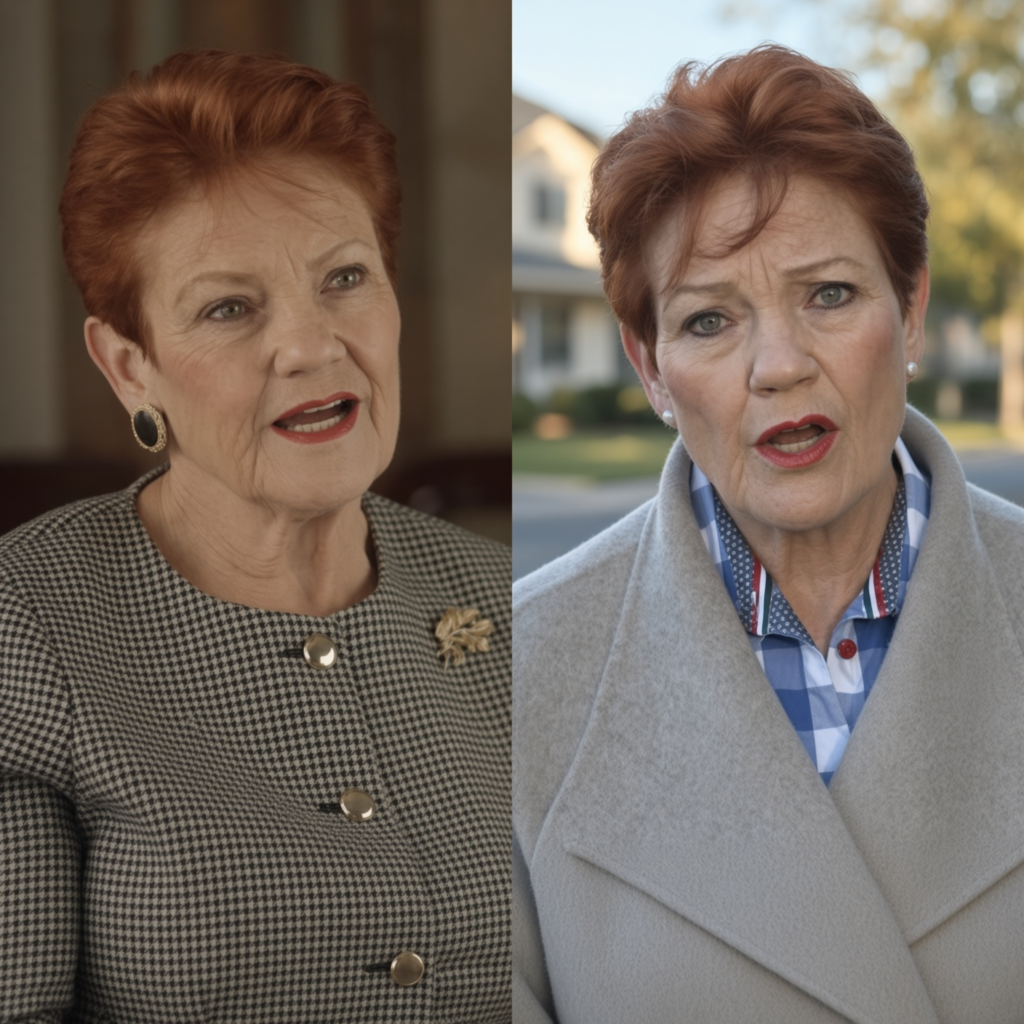
Pauline Hanson has opened the door to a sweeping overhaul of Australia’s compulsory superannuation system, arguing workers struggling with mortgages and the cost of living should have greater access to money being locked away for their retirement.
The One Nation leader’s intervention potentially takes the party’s superannuation policy far beyond its existing proposal to help Australians use super to secure a home.
Hanson says the fundamental principle should be that super belongs to the worker.
“Look, there’s a lot in that one with compulsory superannuation,” Hanson told News24’s Sunday Agenda.
“A lot of Australians are doing it tough now and struggling to pay off their mortgages.”
She said Australians facing immediate financial pressure should have greater ability to use their retirement savings rather than being forced to wait decades to access them.
“In some ways, I feel that you should give them their money now and let them help them with the cost of living,” Hanson said.
“It is their money. They’ve sacrificed it in lieu of pay.”
The remarks have immediately reignited one of Australia’s most consequential economic debates: whether compulsory superannuation should remain primarily preserved for retirement or become a more flexible pool of personal savings that workers can draw upon during major periods of financial pressure.
Australia’s Superannuation Guarantee currently requires employers to contribute 12 per cent of an eligible employee’s ordinary time earnings into super.
The system has accumulated more than $4 trillion in retirement savings and has become one of the largest pools of pension assets in the world.
Its central bargain is straightforward.
Workers sacrifice access to part of their remuneration today so that compound investment returns can build a larger pool of savings for retirement.
Hanson is questioning whether that bargain remains appropriate when some Australians are struggling to keep the roof over their heads now.
Her argument poses a particularly confronting question for households under mortgage stress.
What is the value of preserving hundreds of thousands of dollars for retirement if a worker risks losing their home decades before they retire?
Hanson believes the rules have become too rigid.
She wants them “lightened up a bit” so Australians can access their own money during serious financial difficulties.
The proposal has not yet become a fully designed One Nation policy.
That distinction is important.
Hanson has opened the door to substantial reform, but the party has not published detailed rules setting out exactly who could withdraw money, how much could be accessed, how often withdrawals could occur or whether money taken for general cost-of-living expenses would eventually have to be returned.
Those details would determine whether the proposal amounted to a limited expansion of hardship access or a fundamental restructuring of compulsory superannuation.
One Nation already has a more specific policy covering housing.
Under that model, an individual’s superannuation could be invested by their super fund in their primary residence.
When the property was eventually sold, proceeds corresponding with the superannuation investment would be returned to the fund.
That is materially different from simply withdrawing retirement savings and spending them.
If super becomes an investment in the member’s home, the retirement fund retains an economic interest in an asset.
If money is withdrawn to pay ordinary living expenses and never returned, however, it permanently leaves the retirement system.
Hanson’s latest comments suggest she is willing to consider greater flexibility than One Nation’s existing housing model.
That prospect has alarmed the Albanese Government.
Treasurer Jim Chalmers accused One Nation of threatening the future of Australia’s compulsory superannuation system and warned that weakening preservation rules would damage workers’ long-term economic security.
He characterised the emerging One Nation and Coalition debate over early access as part of an “anti-super” agenda.
The disagreement goes directly to the purpose of superannuation.
Labor sees compulsory super primarily as retirement income.
The logic is that forcing workers and employers to save during a person’s working life produces larger private retirement balances, reduces dependence on the Age Pension and gives retirees greater financial independence.
Under that model, restrictions on early access are not an accidental inconvenience.
They are essential to making the system work.
If people can routinely withdraw money whenever household finances become difficult, balances have less time to compound and retirement savings shrink.
Hanson approaches the issue from the opposite direction.
She argues compulsory contributions ultimately represent workers’ money and questions whether government should exercise such extensive control over when they are permitted to use it.
That argument becomes politically potent during a cost-of-living and housing affordability crisis.
A household can be simultaneously asset-rich in superannuation and cash-poor outside it.
A worker in their 40s or 50s could have a substantial super balance while struggling with mortgage repayments, medical costs or other immediate financial pressures.
Under Australia’s preservation system, having money in super does not generally mean the member can simply withdraw it whenever they choose.
But claims that Australians have absolutely no access to super before retirement are also incorrect.
Existing law already permits early release in a limited range of circumstances.
The Australian Taxation Office administers access on compassionate grounds for specified expenses.
Those circumstances can include certain medical treatment and medical transport costs, palliative care, expenses associated with a dependant’s death, and payments required to prevent foreclosure or forced sale of a person’s principal home.
There are also separate early-access arrangements involving severe financial hardship, terminal medical conditions and incapacity.
The current debate is therefore not really about whether early access should exist.
It already does.
The argument is about how narrow those gates should remain.
Hanson wants them opened further.
Chalmers believes doing so risks undermining the entire retirement-income model.
The difference becomes particularly important for mortgages.
Existing compassionate-release provisions can permit access to super to prevent foreclosure or forced sale of a principal home when the statutory requirements are satisfied.
That is not equivalent to allowing a household experiencing ordinary mortgage stress to routinely use super to meet repayments.
Nor is it equivalent to allowing first-home buyers to use super to purchase a property.
One Nation is contemplating substantially broader flexibility.
Housing is where the argument has the strongest political appeal.
For many Australians, owning a home outright by retirement can be at least as important to financial security as the size of their super balance.
A retiree with a smaller super account but no rent or mortgage can be in a fundamentally different financial position from a retiree with more super who remains exposed to private rental costs.
That is why advocates of super-for-housing policies argue the debate cannot simply compare one super balance with another.
Housing itself is a retirement asset.
Deputy Liberal leader Jane Hume has made a similar argument, saying home ownership is critical to financial security in retirement.
Opposition Leader Angus Taylor has also argued Australians should have greater flexibility over their superannuation.
The issue therefore has the potential to create an unusual area of overlap between sections of the Coalition and One Nation.
Barnaby Joyce has also backed broader access.
Joyce argues compassionate grounds should be expanded, particularly for Australians facing severe housing or financial pressure.
His intervention suggests the debate is moving beyond the familiar argument over first-home deposits and towards the wider question Hanson has now raised: what counts as a sufficiently serious life crisis to justify using retirement savings early?
There are substantial economic objections.
The first is compound returns.
A dollar withdrawn from super at 30 or 40 does not merely reduce the final balance by one dollar.
It also removes decades of potential investment earnings on that dollar.
Repeated withdrawals could therefore leave workers with dramatically smaller retirement balances than the amount initially taken out might suggest.
The second issue is the Age Pension.
If broader early access produces lower retirement balances, some Australians could eventually require greater taxpayer support in old age.
In that scenario, financial pressure is not eliminated so much as shifted across time — from the household today to the federal budget decades later.
Superannuation industry groups have seized on precisely that risk.
The Association of Superannuation Funds of Australia and the Super Members Council have warned that weakening preservation could harm retirement outcomes and increase future reliance on government support.
There is also a lesson from the pandemic.
During COVID-19, the Morrison government temporarily allowed eligible Australians experiencing financial hardship to withdraw up to $20,000 from their super across two financial years.
Millions of Australians used the scheme.
It provided immediate cash at an extraordinary moment of economic disruption, but it also generated a lasting debate over the retirement balances those workers surrendered.
Supporters regarded the scheme as evidence that super can provide a powerful emergency buffer when people genuinely need their own money.
Critics regarded it as evidence of how quickly retirement savings can be depleted when preservation rules are relaxed.
Hanson’s proposal raises another question that COVID early release did not fully resolve: liquidity.
Super funds do not hold every member’s balance as cash waiting to be withdrawn.
They invest in shares, bonds, property, infrastructure, private assets and other investments.
The system works partly because funds can plan around members generally leaving their money invested for long periods.
If substantially larger numbers of members suddenly gained withdrawal rights during an economic downturn, funds could face pressure to maintain more liquid assets or sell investments to meet redemptions.
Economists have warned that the design of any broad early-access regime would therefore matter not only for individual retirement balances but for fund management itself.
There is an equally serious objection to using super for housing.
If governments allow buyers to access additional money without increasing the number of homes available, some economists argue the policy could simply increase purchasing power and push prices higher.
In a supply-constrained housing market, buyers may end up bidding their superannuation against one another.
One Nation attempts to answer that criticism by combining its super policy with other housing measures aimed at increasing supply and reducing demand.
The party advocates lower migration, restrictions on foreign ownership and reductions in government costs associated with new housing.
Its super proposal is therefore intended to sit within a larger housing program rather than operate alone.
Whether that combination would prevent price inflation would depend on how quickly housing supply responded relative to the additional purchasing power released into the market.
There is also a philosophical question beneath all the economics.
How compulsory should compulsory superannuation be?
The Superannuation Guarantee is compulsory precisely because governments concluded that many people would otherwise save too little for retirement.
The system restricts individual choice today in pursuit of greater financial security tomorrow.
Hanson’s position challenges that paternalistic bargain.
If a worker is at risk of losing a house, cannot meet a serious medical expense or is under severe financial stress, she argues that worker may be better placed than Canberra to decide whether money is more valuable now or at age 60 or 65.
Labor’s counterargument is that individual decisions made during periods of financial distress can produce collective consequences decades later.
A worker who drains super today may eventually become a retiree who needs greater taxpayer assistance.
Both arguments concern the same money but define responsibility differently.
Hanson emphasises ownership.
Chalmers emphasises preservation.
That difference is why her phrase “it is their money” is likely to become central to the political battle.
It reduces a technically complex retirement-income argument to a simple question of control.
If super belongs to workers, why should they not decide when they genuinely need it?
The government’s answer is that compulsory preservation is precisely what transforms ordinary wages into long-term retirement capital.
Remove that protection too broadly and compulsory super could gradually become another savings account.
The policy details One Nation has yet to provide will determine which description is closer to what Hanson actually proposes.
A tightly controlled expansion of compassionate access would be an incremental reform.
Allowing withdrawals for mortgage repayments and broad cost-of-living pressure would be much more significant.
Making compulsory contributions optional for some workers would fundamentally alter the Superannuation Guarantee itself.
Those are three very different policies.
Hanson’s latest comments have opened the door to the debate without yet choosing precisely how far One Nation would walk through it.
That uncertainty is important because reports describing the intervention as a call to simply “end compulsory super” go further than the detailed policy One Nation has so far published.
Current reporting says the proposal remains under development, with eligibility rules and withdrawal limits unresolved.
What is clear is that One Nation no longer wants the argument confined to first-home buyers.
Hanson is asking whether Australians facing financial hardship should have greater authority over retirement savings they legally own but generally cannot access.
The Coalition is confronting similar questions within its own ranks.
Labor is drawing a firm line around the compulsory system.
And Australia’s multi-trillion-dollar superannuation industry is warning that what looks like financial relief today can become financial insecurity decades later.
That sets up a potentially major political contest.
For a homeowner struggling to meet the next mortgage repayment, retirement can feel very distant.
For policymakers designing a retirement-income system, those distant decades are the entire point.
Hanson has now placed those two realities directly against each other.
Her challenge is simple: if Australians have sacrificed wages to build their super, she believes they should have greater control over when that sacrifice can be called upon.
The challenge for One Nation is considerably harder.
It must now design rules that provide that freedom without leaving workers poorer in retirement, increasing future pension costs or turning Australia’s compulsory retirement system into a source of cash every time household finances come under pressure.
Until those details are released, Hanson has opened a sweeping debate rather than delivered a finished overhaul.
But after decades in which compulsory preservation has been one of the foundations of Australian retirement policy, even opening that door is politically significant.