Barnaby Joyce has called for Australians who cannot afford food or housing to be given greater access to their superannuation, arguing financial hardship should not have to reach catastrophic levels before workers can use more of their own retirement savings.
The One Nation MP and former deputy prime minister made the case on Monday as the party intensified its push to loosen Australia’s tightly controlled early-access rules amid continuing cost-of-living and housing pressure.
Joyce said Australians already have some ability to access super under hardship provisions but argued the definition should recognise people struggling with basic necessities.
“I think one of the hardships people have is if they can’t feed themselves because of the cost of living,” Joyce said.
He also pointed to housing insecurity.
“And another hardship is if they don’t have a house and they’re put out on the street and they’re living in a car.”
For Joyce, the principle is one of ownership.
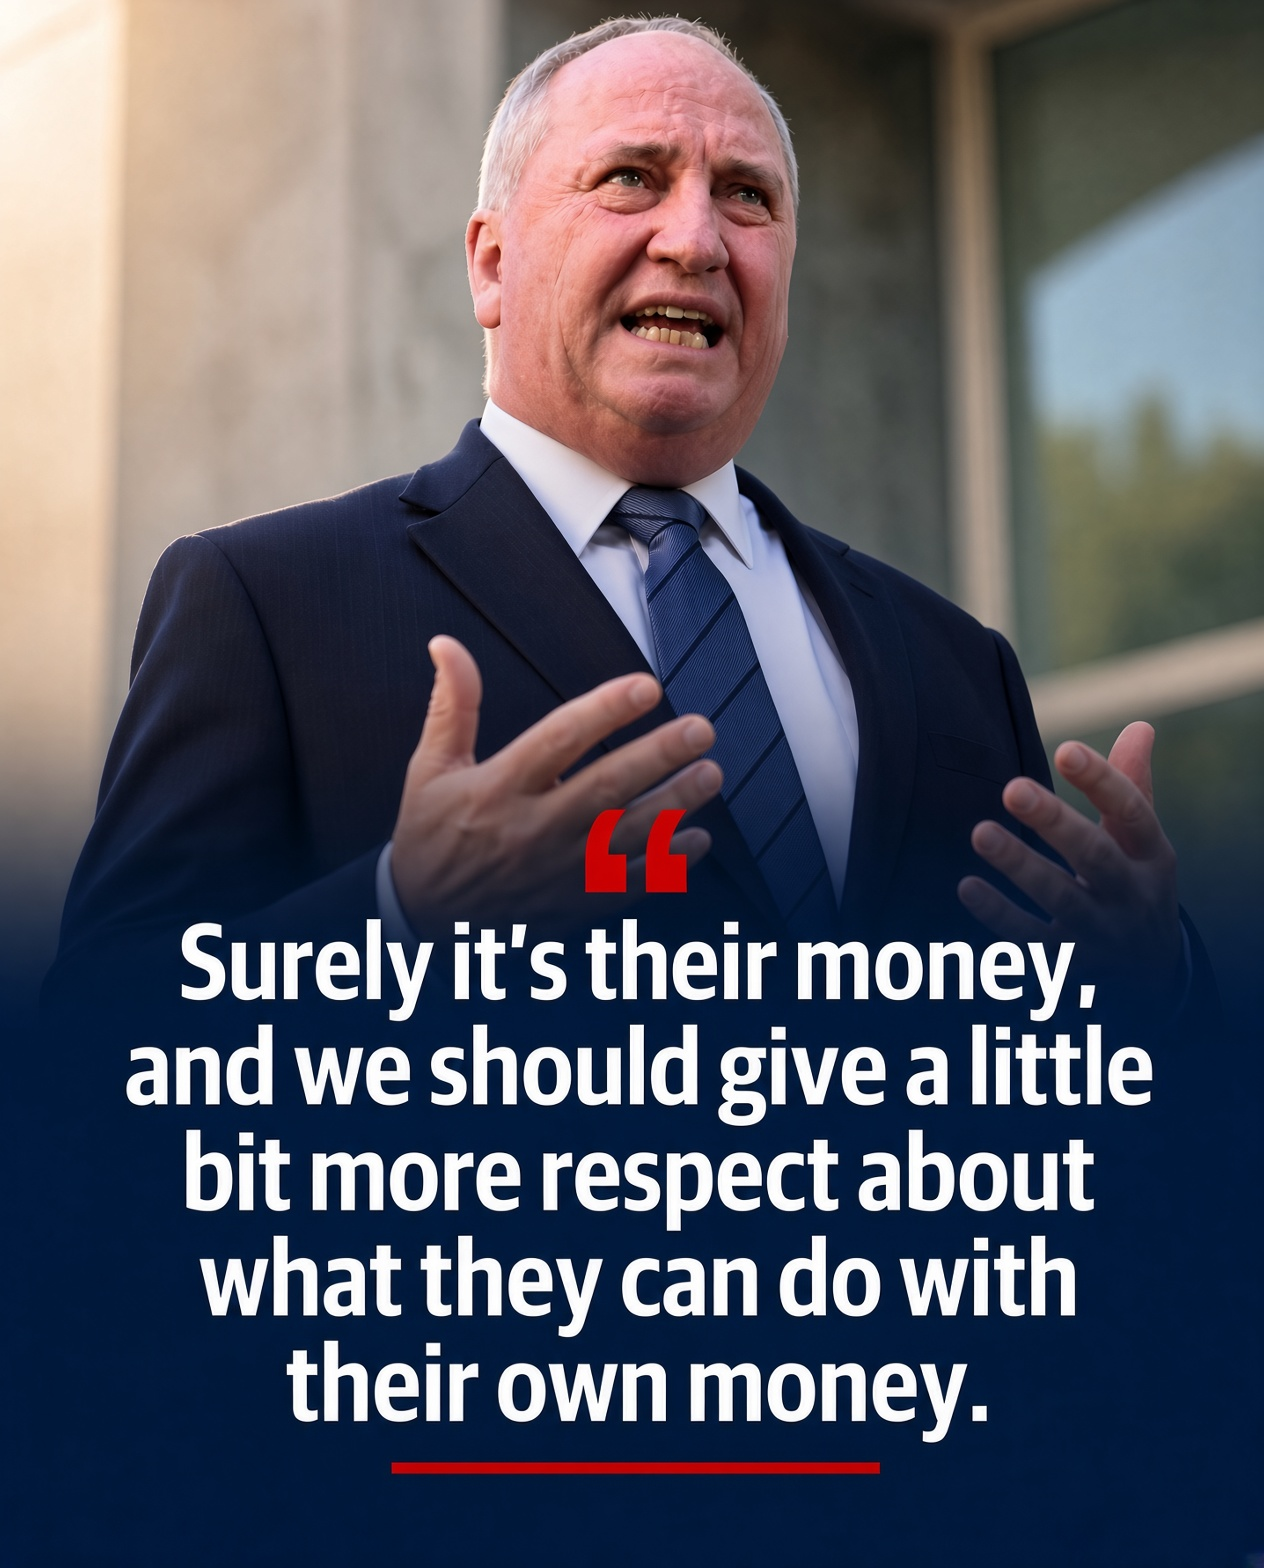
“Surely it’s their money and we should give a little more respect about what they can do with their own money.”
ABC’s live federal politics coverage recorded the remarks on Monday morning, while Joyce made a similar argument during a heated Sunrise debate with Labor frontbencher Tanya Plibersek.
Joyce backs Hanson’s super push
The intervention puts Joyce firmly behind Pauline Hanson’s attempt to make early access to super a major political issue.
Hanson reignited the debate on Sunday when she questioned whether Australia’s compulsory system was giving financially distressed workers sufficient control over savings accumulated in their names.
She pointed particularly to Australians struggling with mortgage repayments.
“A lot of Australians are doing it tough now and struggling to pay off their mortgages,” Hanson said.
Her central argument closely resembles Joyce’s.
Superannuation is ultimately the worker’s money, Hanson argues, and Australians facing serious financial pressure should have more opportunity to use it while they need it rather than being required to preserve almost all of it until retirement.
Current reporting indicates One Nation’s broader proposal remains under development, with important details including eligibility requirements and withdrawal limits yet to be settled.
Joyce’s contribution begins to define what an expanded system might look like.
Rather than focusing exclusively on medical emergencies or buying a house, he is explicitly putting inability to afford basic living expenses and severe housing insecurity on the table.
Australians can already access super for financial hardship
One important qualification is necessary.
Australians do not currently have to be sick or dying before they can ever access super early.
Official Australian Taxation Office guidance says early access is available in a limited range of circumstances, including severe financial hardship, compassionate grounds and terminal medical conditions.
The severe financial hardship pathway is particularly relevant to Joyce’s argument.
Applications on those grounds are made directly to a person’s super fund rather than the ATO.
For superannuation professionals, the ATO states that release under severe financial hardship requires the relevant conditions to be satisfied, including circumstances where the member cannot meet reasonable and immediate family living expenses.
That means the emerging political argument is not over whether financial hardship should have any place in Australia’s super system.
It already does.
The dispute is over whether existing eligibility requirements are too restrictive and should be substantially expanded.
What compassionate access actually covers
Compassionate grounds provide another existing pathway, although they operate differently from severe financial hardship.
The ATO permits compassionate release only for specified expenses and where the eligibility requirements are satisfied.
These can include particular medical treatment and medical transport expenses, palliative care and certain costs connected with a dependant’s death.
There is also an important housing provision.
Eligible Australians may be able to access super on compassionate grounds to make payments necessary to prevent foreclosure or the forced sale of their principal home.
That is significantly narrower than allowing someone experiencing ordinary mortgage stress to routinely draw down their super to make repayments.
It is that gap between serious financial pressure and the existing release thresholds that One Nation wants to turn into a political battleground.
‘It’s their money’
Joyce’s strongest argument is deliberately simple.
The money belongs to the worker.
“Surely it’s their money,” he said.
That message is likely to resonate with Australians who can see substantial balances accumulating in their super accounts while struggling to meet immediate household expenses.
A worker can simultaneously have tens or hundreds of thousands of dollars in super and relatively little accessible cash.
For someone facing rent stress, mortgage arrears or rising grocery and energy bills, a retirement balance can consequently feel like wealth they own on paper but cannot use when it matters most.
Joyce argues government should show greater respect for the individual’s ability to decide how their money is used.
Plibersek pushed back against that position during their Sunrise exchange, defending the purpose of preserving retirement savings and challenging the wisdom of solving today’s financial pressures by reducing the money available later in life.
That disagreement goes to the heart of compulsory superannuation.
Why super is difficult to access
Australia’s system deliberately restricts access to super before retirement.
That is not an accidental feature.
It is one of the mechanisms through which the system creates long-term retirement savings.
Money contributed when a worker is young can remain invested for decades, generating returns which are themselves reinvested.
That compounding effect means the long-term cost of an early withdrawal can be substantially greater than the amount initially taken out.
A worker who withdraws $20,000 does not merely lose $20,000 from their eventual retirement balance.
They also lose whatever investment returns that money might have generated over the following decades.
This is why governments and superannuation industry groups traditionally insist that early withdrawals remain exceptional.
One Nation is challenging whether that long-term protection has become too rigid when households are experiencing severe pressure today.
Food and housing change the argument
Joyce’s choice of examples is politically significant.
He did not frame the debate around discretionary spending.
He chose food and shelter.
If a worker genuinely cannot feed themselves, the argument for preserving every possible dollar for retirement becomes harder to communicate.
The same applies to homelessness.
Someone sleeping in a car while holding a substantial super balance presents an uncomfortable question for a system ostensibly designed to provide that person’s financial security.
One Nation’s argument is that financial security at 67 cannot be considered entirely separately from financial security at 37 or 47.
Labor’s answer is that dismantling preservation rules every time households experience economic pressure would eventually defeat the reason compulsory super exists.
Once cost-of-living pressure becomes a general condition for withdrawal, policymakers also encounter an immediate problem: where should the line be drawn?
There is a substantial difference between a person who literally cannot afford food and someone whose discretionary income has fallen because groceries are more expensive.
There is a difference between homelessness and mortgage stress.
There is a difference between a temporary financial shock and persistent household overspending.
A workable policy would need to distinguish among them.
Chalmers warns against weakening the system
Treasurer Jim Chalmers has responded aggressively to One Nation’s push, arguing broader access threatens workers’ long-term retirement security.
Chalmers accused One Nation of wanting to undermine Australia’s compulsory super system and linked Hanson’s intervention to Coalition figures who have also advocated greater flexibility.
The government’s concern is not merely that individual retirement balances would fall.
Lower private retirement savings can ultimately produce higher public costs.
If workers exhaust significant portions of their super during their working lives, more of them could eventually become reliant on the Age Pension and other taxpayer-funded assistance.
In that scenario, allowing early access does not necessarily eliminate financial pressure.
It transfers part of it from the present to the future.
One Nation’s response is essentially that the opposite can also occur.
A household denied access to its own assets during a crisis could lose a home, accumulate expensive debt or suffer other financial damage that also follows it into retirement.
The housing question is particularly difficult
Housing has become central to the debate because a home is not simply consumption.
It is an asset and, for many Australians, an important component of retirement security.
A retiree who owns their home outright generally faces a very different financial position from one who remains exposed to private rental costs.
That has encouraged One Nation and some Coalition figures to argue that policymakers should not treat maximising super balances as the only measure of retirement security.
Using retirement savings to secure home ownership could reduce one asset — super — while increasing another — housing.
Labor and other critics identify a different danger.
Giving prospective buyers additional money does not automatically produce additional homes.
In a market constrained by housing supply, allowing buyers to draw on super could increase their bidding capacity and push prices higher.
The benefit could then flow partly to existing property owners rather than new buyers.
That argument has become a major part of Labor’s attack on super-for-housing proposals as the debate reignited this week.
One Nation still needs to define its limits
The biggest unanswered questions now belong to One Nation.
Hanson and Joyce have established the principle they support: greater personal control over super during serious financial difficulty.
They have not yet produced all the rules needed to implement it.
Would inability to afford food qualify automatically?
Would applicants need to demonstrate a period of income support?
Would renters facing eviction qualify?
Could someone use super to clear consumer debt?
Would mortgage access begin only when foreclosure was imminent, as compassionate provisions can already address in certain circumstances, or much earlier?
How much could be withdrawn?
Could somebody make repeated applications?
Would different rules apply to a 25-year-old and a 60-year-old?
And would any money used for housing eventually have to be returned to the retirement system?
Those questions determine whether One Nation is proposing a modest expansion of existing hardship provisions or something much more fundamental.
A fight over who should control retirement savings
At its core, the emerging political contest is about control.
Labor argues workers need a system that protects retirement savings partly from the pressure to spend them earlier.
One Nation argues workers deserve greater authority over assets accumulated in their own names.
Both sides can point to genuine risks.
Withdraw too much super too early and Australians can arrive at retirement with inadequate savings.
Lock it away too rigidly and Australians facing serious hardship may be prevented from using an asset that could help them preserve their financial position today.
Joyce has now sharpened that dilemma into its most confronting form.
If an Australian cannot feed themselves, or has nowhere to live except a car, should government policy continue telling them their own money is more important decades from now?
Labor believes broader withdrawals risk creating a larger retirement problem later.
Joyce believes the system needs to show more respect for workers’ ability to make that decision themselves.
What began as Hanson’s call for more flexible superannuation rules is consequently developing into a much larger argument over the purpose of Australia’s retirement system.
And if One Nation wants to take that argument to an election, the next step will be harder than declaring “it’s their money”.
It will have to define exactly when Australians should be allowed to spend it.